FBAR Tax Attorneys: Get Help Filing Your FBAR to Prevent IRS Penalties

Hire an FBAR Attorney for Compliant FBAR Filing

When foreign financial accounts, reporting requirements or potential penalties are involved, having an experienced FBAR attorney on your side can provide a significant advantage. Our full-service tax and accounting law firm brings years of experience to help those who need legal representation.

Silver Tax Group’s legal team helps secure compliance, mitigate massive penalty exposure and defend assets against IRS enforcement.

Unlike tax preparation mills, we provide:

Schedule a Free Consultation Now

Your information is 100% confidential and protected.

Silver Tax Group has a 10/10 rating for being a top tax lawyer.
Silver Tax Group is a top-rated Tax Law firm on FindLaw in 2025.
Chad C. Silver is rated as a Rising Star on SuperLawyers.
Chad Silver is rated 5/5 as an Elite Tax Lawyer.
Silver Tax Group has a 10 star lawyer rating on Justia.
Chad Silver won the 5/5 Stars Lawyers of Distinction Award.
Silver Tax Group has a 5 star rating on BBB.
Silver Tax Group awarded the best US tax law firm in 2025.

Why You Need an FBAR Lawyer, Not Just a CPA or EA

Working with an FBAR lawyer is critical when financial account matters become more complicated. At Silver Tax Group, you work with real tax attorneys, not certified public accountants (CPAs), enrolled agents (EAs) or preparers. On your first call, we tell you exactly where you stand and what it takes to fix it. No guesswork.

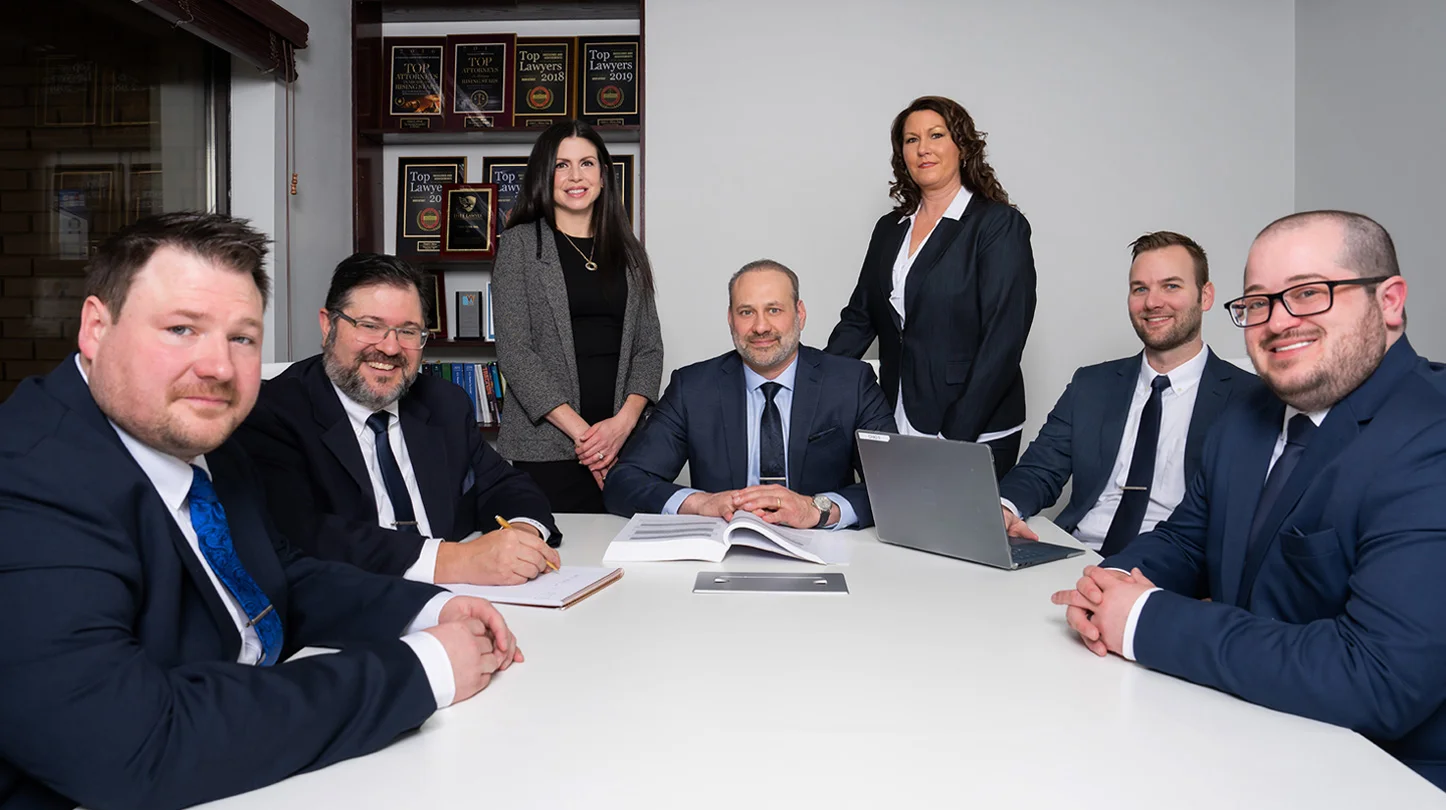
Professional legal team seated at a conference table in formal attire, smiling and ready to assist clients

The Privilege Gap

CPAs can be forced to testify against their clients if a case turns criminal. Only an FBAR tax attorney provides full attorney privilege, which creates an important layer of confidentiality that traditional tax preparation services may not offer. 

Litigation Authority

If an audit escalates, CPAs generally cannot represent clients in the U.S. Tax Court. At Silver Tax Group, our attorneys are admitted to the Tax Court and the State Bar. Since we are qualified to represent eligible clients, we can help you understand the broader legal and tax implications and develop an appropriate strategy surrounding your obligations. 

Strategic Disclosure

Filing a late FBAR without first evaluating your facts can increase penalty risk, especially if the IRS questions whether your violation was nonwillful or willful. We architect the disclosure strategy before filing anything. Our tax attorneys have filed thousands of FBARs and eliminated millions in penalties.

Our Role as Your FBAR Filing Attorney

Here’s how our team helps clients address filing requirements, penalty exposure and IRS contact:

Why Clients Choose Our Tax Law Firm

Our clients come to us when the stakes are high. Every day, taxpayers, business owners, professionals, crypto investors and high-income earners come to us when they can’t afford mistakes. They trust Silver Tax Group for one reason: we get results.

U.S. Tax Court Admission

Our managing partner is fully admitted to practice before the U.S. Tax Court. This admission gives qualifying clients access to an attorney who can represent them in federal tax litigation when a dispute goes beyond filing and compliance. This distinction matters so you don’t have to find a separate attorney if litigation becomes necessary.

Elite Legal Credentials

We understand that foreign account reporting can raise questions involving disclosures, penalties and potential legal exposure. Our FBAR attorneys know how the tax law works, evaluating key issues while considering the underlying financial information. Our firm combines professional legal credentials, years of licensed tax practice experience and accounting knowledge to provide a more comprehensive approach to complex tax matters.

National Professional Membership

Tax regulations and IRS procedures can change, so we maintain memberships in national professional organizations to keep our team current on developments in tax law and practice. Our active standing in the American Bar Association (ABA) and the National Association of Tax Professionals (NATP) reflects our commitment to professional standards and continued education.

Proven Litigation Track Record

Our tax law firm brings a strong track record in FBAR compliance, helping clients save over $128,000,00 through representation and strategic amnesty disclosure. Our decades of combined tax law experience mean we are prepared to advocate for eligible clients when a case requires representation.

Transparent Flat-Fee Pricing

We offer predictable, flat-fee structures for offshore disclosures, avoiding the notorious hourly-billing traps of big-box firms. This straightforward pricing helps clearly define the scope of work and what you can expect before moving forward.

Why Clients Choose Our Tax Law Firm

Our clients come to us when the stakes are high. Everyday taxpayers, Business owners, professionals, crypto investors, and high-income earners who can’t afford mistakes. They trust Silver Tax Group for one reason: we get results.


Man in a blue suit and tie against a dark background.

Led by
Chad C. Silver, Esq.

Chad C. Silver, Managing Partner, has dedicated his career to defending taxpayers from aggressive IRS enforcement. He is a member of the National Association of Tax Professionals (NATP) and the American Bar Association (ABA), and is admitted to practice before the United States Tax Court and the State Bar of Michigan.

Chad authored Stop the IRS, a guide for individuals and business owners seeking to understand and resolve federal tax issues. His leadership drives Silver Tax Group’s mission—to deliver lawful, strategic, and permanent solutions for clients across the nation.

What Is FBAR, and Who Has to File?

FBAR stands for Report of Foreign Bank and Financial Accounts. You file this form when your foreign accounts total more than $10,000 at any time during the year.

The $10,000 limit applies to all your foreign accounts combined, not each account separately. For example, if you have $6,000 in a London bank and $5,000 in a Toronto investment account at the same time, you crossed the $10,000 limit and must file.

U.S. citizens, residents, corporations, partnerships, LLCs, trusts and estates all need to file FBAR when they meet the requirements.

Who We Help With FBAR Compliance

We handle all FBAR filing needs for individuals, businesses and trusts with foreign accounts. Our tax attorneys prepare this year’s filings, fix missed filings from past years, defend against penalties and represent you during IRS audits. When you work with our attorneys, the attorney-client privilege protects what you tell us. CPAs and tax preparers don’t have this same protection.

You have foreign investment accounts, offshore bank accounts or foreign entities tied to real estate that may create reporting obligations. Missing FBAR filings could cost you hundreds of thousands in penalties. We handle your filings correctly to meet all IRS requirements while keeping your financial information as private as the law allows.

You just learned about FBAR filing requirements, maybe years after you should have filed. If the IRS has not contacted you yet, you may still have options to correct missed FBAR filings. The right path depends on whether your conduct was nonwillful, whether foreign income was reported and whether reasonable-cause arguments are available.

You’re a citizen of both the U.S. and another country. You have bank accounts, retirement accounts or investments in your home country. U.S. law requires you to file FBAR even if you live abroad or think of yourself as mainly a citizen of another country.

You can sign checks or move money in foreign business accounts as an officer, employee or authorized signer. You must file FBAR personally even if you don’t own the account. This applies to corporate accounts, partnership accounts and any client accounts you control.

You moved overseas for work, retirement or family reasons. You opened local bank accounts to pay bills and handle daily expenses. Even though you live outside the U.S., you must still file FBAR if your foreign accounts total more than $10,000. We help expats meet U.S. filing requirements while living abroad.

You inherited money from a relative who lived overseas, or someone gave you a large gift from a foreign account. Inherited foreign accounts may put you over the $10,000 FBAR filing threshold, while large foreign gifts or inheritances may trigger separate reporting requirements. We help you report inherited accounts and foreign gifts correctly to avoid penalties for accounts you didn’t even know you needed to report.

Missed Past FBAR Deadlines? We Can Help.

See which late-filing option may fit your situation. After the IRS removed its public webpage for the former Delinquent FBAR Submission Procedures (DFSP) in 2026, taxpayers should not assume that late FBAR filing will automatically result in penalty relief. Get help from our FBAR attorneys to evaluate the right strategy. We've helped hundreds of clients resolve past noncompliance with minimal penalty exposure.

Discuss Late Filing Options

Complete FBAR Filing Services From Licensed Tax Attorneys

As part of our international tax services, we support individuals, businesses and trusts with current filings, late filings, penalty defense and IRS audit representation.

Current Year FBAR Filing

For current filings, our attorneys handle the details needed to complete and submit FinCEN Form 114.

Late FBAR Filing and Penalty Relief

If you missed prior deadlines, we evaluate the available correction paths and prepare the required filings.

FBAR Penalty Defense

When penalties are assessed or threatened, we help build the strongest available defense.

IRS Audit and Examination Defense

If the IRS contacts you, our team can manage communications and protect your position throughout the process.

Related International Tax Forms

Depending on your situation, FBAR compliance may also involve related international tax forms, including:

  • ✓Form 8938 (report foreign financial assets over $50,000)
  • ✓Form 3520 (report foreign trust transactions and gifts)
  • ✓Form 5471 (report ownership in foreign corporations)
  • ✓Form 8865 (report foreign partnership interests)
  • ✓Schedule B (answer foreign account questions on tax return)

How Our FBAR Filing Process Works From Consultation to Submission

We handle everything from collecting your account statements to filing electronically with FinCEN. Our process finds ways to reduce or eliminate penalties while keeping your information protected. Current-year filings take 2-3 weeks. Fixing missed filings from past years takes 4-8 weeks depending on how complex your situation is.

Step 1: Free Private Consultation and Case Review

We review your foreign accounts, check what you need to file and look at any missed filings. Our FBAR tax attorneys figure out which accounts you need to report, whether you qualify for penalty reductions and get fully compliant. You get answers about what you need to file, the timeline, possible penalties and our pricing.

Step 2: Collect Your Foreign Account Statements

We compile statements showing your highest account balances during the year. For this year’s filing, you give us statements from all your foreign banks. For missed filings from past years, we collect 6 years of statements. We help you get old statements from foreign banks.

Step 3: Prepare Your FBAR and Check Everything

We fill out FinCEN Form 114 with account details, calculate balances and mark account ownership. We validate the $10,000 filing requirement and check if you need to file Form 8938 (FATCA). For late filings, we prepare everything, including amended tax returns and statements explaining why you filed late.

Step 4: File Electronically Through FinCEN's System

We submit your FBAR online through FinCEN. You get a confirmation email and a filing receipt. For current-year filings, we make sure everything is filed timely. For late filings, we prepare the required submission materials and help document the facts supporting your correction strategy.

Step 5: Watch for IRS Letters and Handle Any Follow-Up

After filing, we watch for letters from the IRS. If the IRS contacts you, we handle everything. For clients using penalty relief programs, we answer IRS questions and negotiate to reduce penalties. We set up reminders for your yearly FBAR filings and stay available if you open new foreign accounts or have questions about reporting changes.

Step 6: Your FBAR Compliance Is Complete

Your FBAR filing is accepted, and you’re in full compliance with IRS requirements. If your correction strategy involves Streamlined Procedures or another penalty-relief path, we help you monitor for IRS follow-up and respond if the agency requests more information. You receive copies of all filed forms for your records. We stay available if you have questions or need help with next year’s filing.

FBAR Penalties: What You Face for Not Filing

Missing FBAR filings can create serious penalty exposure. FBAR penalties fall into two types: unintentional and intentional. The difference determines whether you pay thousands or millions in penalties. 

Nonwillful Penalty

A nonwillful penalty may apply when the failure came from negligence, an honest mistake or a good-faith misunderstanding of the law. For penalties assessed on or after January 17, 2025, the inflation-adjusted maximum for a nonwillful FBAR violation is $16,536.

After the Supreme Court’s decision in Bittner v. United States, a nonwillful failure to file a compliant FBAR is generally treated as a single violation per annual report, not per account.

Willful Penalty

A willful penalty may apply when the taxpayer knowingly violates the filing rule or recklessly ignores it. Hence, it carries much larger penalties up to the greater of the inflation-adjusted statutory amount or 50% of the balance at the time of the violation.

We help clients file current FBARs, correct past noncompliance through voluntary disclosure programs and defend against IRS penalty assessments.

How the IRS Decides If You Hid Your Accounts on Purpose

The IRS looks at several things when deciding if your FBAR violations were intentional:

  • ✓Did you check “yes” to the Schedule B foreign account question on your tax return but not file FBAR? This shows you knew about the offshore accounts.
  • ✓Did you get professional tax advice that mentioned FBAR?
  • ✓Did the accounts earn income you didn’t report?
  • ✓Did you use the accounts for transactions meant to hide them?
  • ✓Did you open accounts in countries known for bank secrecy?
  • ✓Did you hold accounts through fake companies or other people’s names?

Even wealthy people with complex finances can prove their mistake was honest with the right documentation and legal arguments.

Criminal FBAR Penalties and Jail Time

Intentional FBAR violations can lead to criminal charges. Maximum criminal penalties include up to 5 years in federal prison and fines up to $250,000. The IRS Criminal Investigation Division pursues criminal cases when they suspect you deliberately hid foreign accounts.

Timely voluntary disclosure may reduce criminal exposure in qualifying cases. Eligibility generally closes after the IRS starts an examination or investigation. A tax attorney should review the facts before any filing. This makes early consultation with a tax attorney critical when you discover past missed filings.

Review Your Correction Options Before You File

Taxpayers with missed FBAR filings may have several correction paths, but the right option depends on the facts. After the removal of the former DFSP, late-filing decisions require more careful legal analysis.

We look at your accounts, how many years you missed and whether you reported the income. Then we recommend the path that will likely result in the lowest penalties.

1. Delinquent or Amended FBAR Filing With Reasonable-Cause Support

If foreign-account income was properly reported but FBARs were missed, filing delinquent or amended FBARs with a strong reasonable-cause explanation may be appropriate. Still, taxpayers should not treat penalty relief as automatic.

2. Streamlined Filing Compliance Procedures for Nonwillful Conduct

These procedures may be available to eligible taxpayers whose failures resulted from nonwillful conduct. Two versions exist based on where you live:

Both programs require you to sign a statement saying you didn’t hide your accounts on purpose, you just made an honest mistake or didn’t know the rules.

3. IRS Voluntary Disclosure Practice for Intentional Hiding

If the facts suggest willful conduct, reckless disregard or potential criminal exposure, the IRS Criminal Investigation Voluntary Disclosure Practice may be the safer path to evaluate. This process can help reduce criminal exposure in qualifying cases, but it does not guarantee immunity from prosecution.

The IRS may consider your actions intentional when you got advice about FBAR but didn’t file, you answered “yes” to foreign account questions on Schedule B but skipped filing FBAR, or you moved money around to stay under the $10,000 limit.

Common Questions & Answers About FBAR Filing and Compliance

What is the FBAR filing deadline?

The FBAR filing deadline is April 15 each year, with an automatic extension to October 15 requiring no formal request.

Unlike tax return extensions that need Form 4868, the FBAR extension is automatic. You don’t file anything to get the October 15 deadline. However, the IRS can still charge late filing penalties if you miss October 15. Natural disasters can extend deadlines even further in affected areas. See our FBAR reporting guide for more information.

Do I need to file FBAR if I already reported my foreign accounts on my tax return?

Yes. Reporting foreign account income on your tax return does not replace the separate FBAR filing requirement through FinCEN’s system.

FBAR and your tax return are separate filings that go to different agencies. Your tax return goes to the IRS. FBAR (FinCEN Form 114) goes to the Financial Crimes Enforcement Network. You must file both when your foreign accounts total more than $10,000. Many taxpayers face penalties because they thought reporting the income was enough, even though they paid all taxes owed.

What happens if I file my FBAR late?

Late FBAR filing can result in civil penalties, but the amount depends on the facts and whether the violation was nonwillful or willful. Willful penalties can be much higher.

How does the IRS find out about unreported foreign accounts?

Foreign banks report U.S. account holder information to the IRS through FATCA information exchange agreements with foreign governments.

The Foreign Account Tax Compliance Act requires foreign banks to report accounts held by U.S. persons or face big penalties. Over 100 countries participate in automatic information exchange. The IRS receives detailed reports including account holder names, addresses, taxpayer ID numbers, account balances and transaction information. Swiss bank secrecy no longer protects U.S. taxpayers. Banks in the Cayman Islands, Singapore, Hong Kong and other offshore locations report to the IRS.

Can I file FBAR myself, or do I need a tax attorney?

You can file FBAR yourself through FinCEN’s online system, but tax attorneys provide representation benefits that CPAs and tax preparers cannot offer.

Figuring out filing requirements, calculating total balances, identifying accounts where you can sign checks, and coordinating with Form 8938 requirements needs tax expertise. For late filings, voluntary disclosures, or penalty defense, attorney representation provides privilege protection and negotiation power. The IRS cannot force us to share what you tell us about past missed filings.

What is the difference between FBAR and Form 8938?

FBAR reports foreign financial accounts to FinCEN when total balances exceed $10,000, while Form 8938 reports specified foreign financial assets to the IRS.

FBAR and Form 8938 have different filing limits, go to different agencies and cover partly overlapping asset types. Form 8938 limits are generally higher than FBAR thresholds and vary based on filing status and whether you live in the U.S. or abroad. Form 8938 is filed with your tax return. Form 8938 includes some assets FBAR doesn’t cover, like foreign stock held directly. Many taxpayers must file both forms for the same accounts.

How much does FBAR filing cost with a tax attorney?

FBAR filing fees range from several hundred dollars for current-year filings to several thousand for fixing multiple years of missed filings.

Current-year FBAR filing for straightforward situations typically costs $500 to $1,500 depending on the number of accounts and complexity. Fixing multiple years through Streamlined Procedures costs $3,000 to $8,000 depending on the number of years, accounts, and whether you need amended tax returns. IRS audit defense and penalty reduction requests are priced separately based on case complexity. We provide flat-fee quotes before starting work.

Can the IRS seize my foreign bank accounts for FBAR violations?

Yes, the IRS can levy foreign bank accounts to collect unpaid FBAR penalties after completing the examination and assessment process. The IRS can also seize domestic assets to satisfy FBAR penalty assessments. Getting in compliance before penalty assessment provides the best protection.

Schedule Your Free FBAR Compliance Consultation Today

Secure attorney-client privilege quickly before the IRS initiates an audit or investigation. At Silver Tax Group, we offer a comprehensive review of your offshore penalty exposure and a clear legal roadmap. Our tax attorneys provide confidential consultations to evaluate your filing requirements, penalty exposure and compliance options.

Call us at 855-900-1040 or contact us online to request a privileged case evaluation today. Our legal team will evaluate your FBAR status and provide a flat-fee representation quote to help you get started.

What tax help do you need?

Get Tax Help Now

Call now or fill in the form below to get help with your tax and IRS issues today.